Global experience shows monetary sovereignty is built patiently through reserves, infrastructure and credible alternatives
Published Date – 4 October 2026, 10:34 AM
By Chandu Kumar Potti
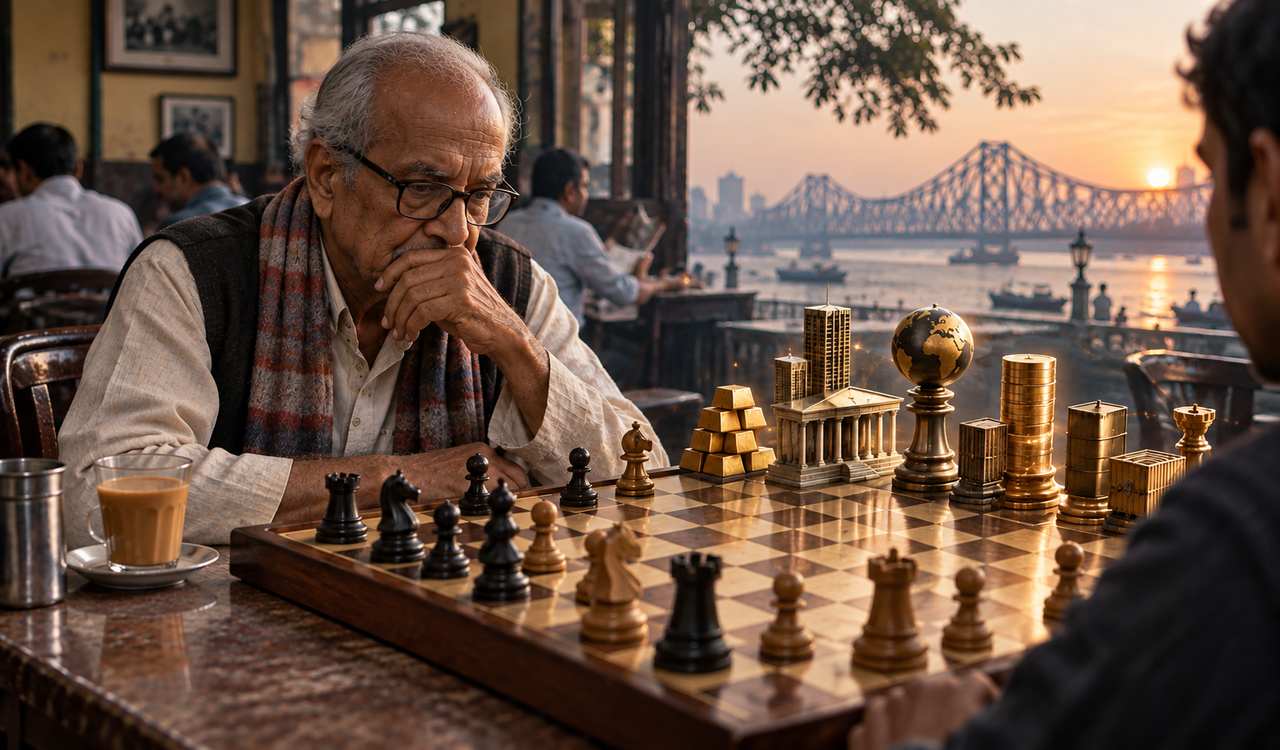
In a coffee shop in Kolkata, an old man plays chess.
He arrives early. Orders tea. Sets up the board. He has been playing in this corner for thirty years, against whoever sits across from him.
He rarely moves quickly. While his opponent reacts to the last move, the old man is already thinking about the position fifteen moves from now.
His grandson once asked him: Dadu, who wins?
The old man smiled. The one who thinks furthest ahead.
He was not talking about chess.
What Chanakya Said About The Treasury
Chanakya’s Arthashastra, written over two thousand years ago, captures this principle clearly: a ruler without a treasury cannot maintain an army, and without an army cannot protect territory. The treasury is the root of all state activity.
He ranked the treasury, Kosha, as the second pillar of state power. Before the army. Before the territory itself.
Monetary sovereignty is not an accident. It is built deliberately. Over time. Through patient accumulation of real assets and real alternatives.
Some nations have been making those moves quietly for twenty years.
China: The Patient Dragon
In 2009, China held approximately 1,054 tonnes of gold in its official reserves.
By Q1 2026, the People’s Bank of China officially declared 2,313 tonnes. Eighteen consecutive months of reported gold purchases. Every month. Without announcement. Without drama.
Credible analysts, examining withdrawal data from the Shanghai Gold Exchange, estimate China’s actual gold holdings may be significantly higher than officially declared. These estimates remain contested and should be treated as informed analysis, not established fact. But the direction of the official data alone tells a clear story: patient, consistent, deliberate accumulation over two decades.
India has built formidable payment infrastructure, but the deeper challenge is preparing reserve-level alternatives before global monetary pressures become urgent.
Alongside gold, China has been building parallel financial infrastructure.
In March 2025, the mBridge cross-border payment system went live, connecting sixteen nations across Asia and the Middle East. Transactions that take three to five days through SWIFT settle in seconds through mBridge. Fees are a fraction of conventional correspondent banking.
Approximately ninety percent of trade between China and Russia is now settled in yuan or rubles, the dollar largely absent from that relationship.
None of this happened overnight. The Shanghai International Energy Exchange, which allows oil to be priced and settled in yuan for the first time, was launched in March 2018. It is now the third most traded crude benchmark globally. The yuan’s share of actual global oil settlement remains small, but the infrastructure and precedent now exist. The digital yuan has been in domestic pilot since 2020.
Each piece positioned quietly. Each move prepared before the next.
The old man in Kolkata would recognise the approach.
Europe: The Proof That Alternatives Are Possible
Before China, there was Europe.
The Euro was not launched on impulse. It was prepared for over a decade, from the 1989 Delors Report, through the 1991 Maastricht Treaty, to the 1999 launch. Ten years of institutional preparation before a single Euro note was printed.
Today the Euro holds approximately twenty percent of global foreign exchange reserves. It is the only currency in the modern era to have achieved meaningful reserve status alongside the dollar.
It proved something important: building a genuine monetary alternative is possible. It requires patience. It requires decades. It requires preparation that begins long before the need becomes urgent.
India: What Has Been Built
India has not been idle.
UPI is live in more than eight countries. In January 2026, it processed 21.7 billion transactions worth approximately Rs 28 lakh crore in a single month. NPCI International is helping twenty-three nations build their own instant payment systems, exporting India’s model, not just its product.
Approximately ninety-three percent of India’s oil imports from Russia now settle in rupees. Import settlements in rupees grew forty-one percent year-on-year in 2025-26.
The RBI bought 73 tonnes of gold in 2024, more than four times the previous year. In June 2024, India repatriated 100 tonnes of gold from storage in the United Kingdom, the first such repatriation since 1991.
These are real, deliberate steps toward reducing dollar dependency.
But here is the honest question that reading China’s preparation and Europe’s preparation raises:
UPI operates at the retail payment layer, tourists, NRIs, daily commerce. Genuinely impressive at that layer.
China’s preparation has been at the reserve layer, central bank gold, wholesale settlement infrastructure, commodity pricing. Europe’s preparation was at the reserve layer, a currency that central banks actually hold.
The dollar dependency this series has described, the invisible tax on Lakshmi’s kitchen, Sirajuddin’s loom, the Bihar farmer’s fertiliser, operates at the reserve and wholesale layer. That is where the pressure lands when the system shifts.
The Question Worth Sitting With
The old man in Kolkata wins because he thinks furthest ahead.
Not because he is cleverer. Not because he has more pieces. Because he begins preparing for the endgame while his opponent is still reacting to the last move.
India has been building. That is true and deserves honest acknowledgment.
The question is whether India is building with the same patience, and at the same layer, as those who have been thinking furthest ahead.
(The author is Founder & Chairman, Versatile Auto Components Pvt Ltd, Versatile Electric Automotive Private Limited, Former Chairman, Pashamylaram Industrial Park and Founding Secretary, Society for Sangareddy Security Council)